Top 3 Singapore Industrial Stocks to Watch in November 2026
Seatrium, Keppel and Yangzijiang screen well on yield, valuation and momentum, but they carry very different risks.
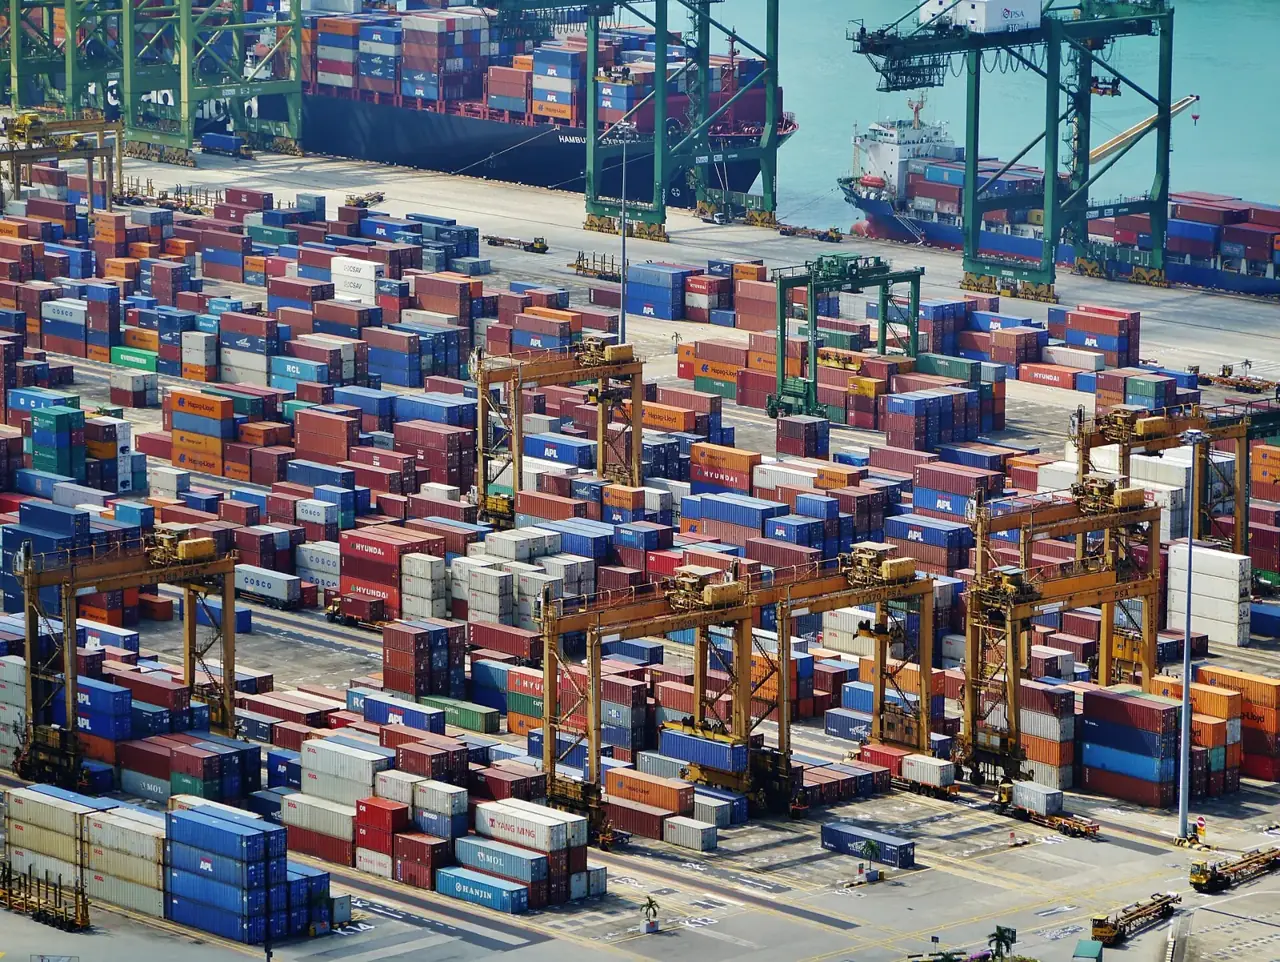
Industrials are no longer the quiet corner of the Singapore market. They have overtaken REITs to become the second-largest sector in the Straits Times Index, and brokers now describe industrial names as the main engine of index earnings growth, helped by record order books at companies such as ST Engineering (SGX: S63) and Yangzijiang Shipbuilding (SGX: BS6).
The backdrop matters for anyone holding these shares. Singapore’s economy grew 5.4% year on year in the third quarter, according to advance estimates, moderating from 6.2% in the second quarter. Manufacturing growth slowed to 7.5% from 12.9%, while construction accelerated to 8.8%. The Monetary Authority of Singapore kept policy unchanged at its October review, with core inflation forecast at 1.5% to 2.0% for 2026.
Rates have also turned friendlier. The 10-year Singapore government bond yield slipped 23 basis points to 2.24% in October, and the US Federal Reserve held its policy rate at 3.75% on 28 October. Lower long-term yields tend to help companies that fund long-dated projects and asset managers whose valuations are sensitive to discount rates.
Yet the mood has cooled. The Straits Times Index closed at 5,289.66 on 11 November, up 13.61% for the year but 8.83% below its 52-week high, with a 14-day RSI of 33.2. October was rough: the index fell 2.32% as investors grew sceptical about returns on AI investment following the cancelled Firmus listing, and shipyard stocks dropped 8.8% over the month. All three names below are lower over the past month.
How we picked these three
The three were drawn from our industrials watchlist using a deliberately simple scorecard: dividend yield, trailing P/E, price to book and one-month price momentum. Each stock is ranked on all four measures and the three with the strongest combined standing made the cut. No single metric decides the outcome, which is why a stock can top the yield table and still sit mid-pack overall. It is a screen for further reading, not a verdict.
Seatrium (SGX: 5E2): a backlog story waiting on orders
Seatrium builds and upgrades offshore production vessels, gas carriers and naval ships, plus a repair and upgrade business. Earnings follow project execution: the group books revenue as milestones are hit, so margins depend on contract mix and how quickly legacy, loss-making work rolls off.
The first half of FY2026 showed the tension. The net order book stood at S$13.3 billion in July, down from S$17.8 billion at end-2025 after a quiet run of major awards, and reported gross margin was 8.6%, short of management’s mid-teens target. Since then contract flow has picked up: over S$500 million of rig completion work from Keppel’s RigCo in late October, a floatover integration contract worth more than S$200 million from SBM Offshore, Karpowership powership conversions and an Excelerate FSRU conversion. Management also doubled its buyback programme to S$200 million.
At S$1.86, the stock trades at 11.62 times earnings and 0.86 times book, with a 1.61% yield. It sits below its 200-day moving average of S$2.14 and 25.0% off its 52-week high, while the RSI of 53.5 is neutral.
The strength is the balance sheet and the pipeline: net gearing below 0.1 times at the half-year stage, plus more than S$32 billion of opportunities management has flagged across oil and gas, offshore wind and conversions. The risk is timing. Rig work for RigCo is understood to be on a cost-recovery basis, so it adds revenue and backlog coverage faster than profit, and the margin recovery still depends on a small number of large awards landing in the next few quarters. The third-quarter business update is scheduled for 19 November.
Keppel Ltd (SGX: BN4): an asset manager with an industrial core
Keppel is mid-transformation. The core, or “New Keppel”, runs asset management plus infrastructure, connectivity and real estate businesses. The legacy non-core portfolio, including old rig assets, sits separately and is being monetised.
The 29 October update showed both halves clearly. New Keppel net profit rose close to 15% in the third quarter and more than 20% over nine months, led by connectivity and steady infrastructure earnings. Funds under management passed S$100 billion in July, ahead of schedule, with about S$19.5 billion added in the year to date. Asset management fees reached S$354 million over nine months, up 18%. The 600MW Keppel Sakra Cogen plant, which started operating in late May, lifted generation capacity by 45%, while the technology solutions arm inside connectivity grew EBITDA 110%.
Reported group numbers were messier. Overall net profit for nine months fell 40% because of impairments, depreciation and holding costs on non-core assets still on the books. That drag helps explain a trailing P/E of 22.52, well above the other two names, with the shares at S$9.91, 1.77 times book and a 3.48% yield. It is 24.75% below its 52-week high, below its 200-day average of S$11.30, with an RSI of 43.5.
The strength is recurring income and capital recycling: around S$3.7 billion of transactions announced this year, roughly S$940 million realised so far, with special dividends targeted at 10% to 15% of realised proceeds from non-core sales. Ordinary dividends will now be based on New Keppel earnings. The risk is execution on that separation. Remaining non-core assets continue to blur headline profit.
Yangzijiang Shipbuilding (SGX: BS6): record orders, cyclical share price
Yangzijiang builds container ships, bulk carriers, tankers and gas carriers at yards in China. Earnings depend on newbuild prices, the mix of vessels under construction, delivery volumes and the yuan.
Its 10 November update was the strongest of the three. Year-to-date order wins reached US$6.98 billion, about 55% above the FY2026 target of US$4.5 billion, with 87 vessels signed. The order book stood at US$26.3 billion as at 31 October, a record, with deliveries scheduled through 2030 and roughly two thirds of contract value in clean energy vessels. The group delivered 47 ships against a full-year target of 58, and its new Hongyuan yard is due for completion by end-2026 with first deliveries in 2027.
Despite that, the shares trade at S$4.61, down 9.43% over the past month and the weakest momentum of the three, though still up 33.62% this year. Valuation is 10.02 times earnings and 2.86 times book, with a 4.36% yield. The RSI of 35.6 is the lowest of the group and the price sits above its 200-day average of S$4.17.
The strength is visibility: a decade-long backlog and order intake running well ahead of plan give revenue cover that few Singapore industrials can match. The risk is cyclicality and price. The 2.86 times book is the richest of the three and already reflects several good years, so a downturn in newbuild prices or slower fleet renewal would hit both earnings and the multiple. Yard ramp-up and delivery execution at Hongyuan also bear watching.
| Stock | Price | P/E | P/B | Dividend yield | 1-month change | YTD change |
|---|---|---|---|---|---|---|
| Seatrium (SGX: 5E2) | S$1.86 | 11.62 | 0.86 | 1.61% | -4.62% | -14.29% |
| Keppel (SGX: BN4) | S$9.91 | 22.52 | 1.77 | 3.48% | -4.99% | -4.44% |
| Yangzijiang (SGX: BS6) | S$4.61 | 10.02 | 2.86 | 4.36% | -9.43% | +33.62% |
| Straits Times Index | 5,289.66 | n/a | n/a | n/a | -2.32% | +13.61% |
The bottom line
The three share a sector label but little else. Yangzijiang is the earnings and income story: cheapest on P/E, highest yield, biggest backlog, and the only one up this year. It is also the most cyclical and the most expensive on book value, which is what you would expect after a strong run.
Keppel is the transformation story. It offers the middle ground on yield, but the headline numbers are distorted by legacy assets, so investors need to decide whether they are valuing New Keppel or the whole group. That distinction is the single most important thing to understand before forming a view.
Seatrium is the recovery story. It has the lowest price to book of the three, a repair business that generates cash, and a large opportunity pipeline, but its earnings still depend on converting pipeline into contracts and lifting margins toward the mid-teens. It carries the widest range of plausible outcomes.
In general terms, an investor who wants income and is comfortable with cyclical swings may look at the shipbuilding and asset management names differently from one who is focused on balance sheet value and a margin turnaround story. The scorecard here is a starting point for that work, not a substitute for it.
Sources
- Strategy: Monthly Market Radar | Research | UOB Kay Hian Singapore
- Keppel’s business update for 3Q & 9M 2026 - Keppel - Global asset manager and operator creating solutions for a sustainable future
- Yangzijiang Shipbuilding’s order-wins exceed target by 55%
- Yangzijiang Shipbuilding secures $6.98b in 2026 orders, exceeding annual target
- Keppel’s $500 mil contract and energy infrastruture needs are positives for Seatrium